Compound Interest Calculator - Frequently Asked Questions
The more you learn, the more you earn.
There are different ways to calculate compound interest depending on your needs. Our compound interest calculator uses advanced financial formulas to account for both the growth of the initial principal and the impact of regular contributions.
The Complete Formula:
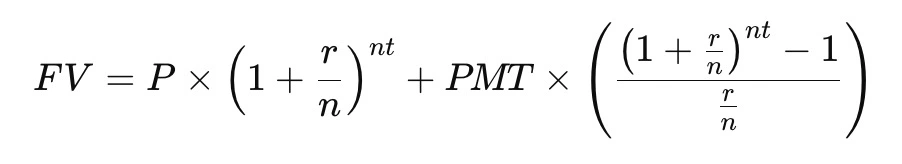
Key Variables:
- FV: Future Value (final amount)
- P: Principal (initial deposit)
- r: Annual interest rate (as decimal)
- n: Compounding frequency per year (daily=365, monthly=12, etc.)
- t: Time period in years
- PMT: Regular payment/contribution amount per period
The calculator accounts for different compounding frequencies and regular contributions, so you can compare scenarios on the same inputs.
Daily (n=365)
Interest calculated 365 times/year. Common for high-yield savings accounts.
Monthly (n=12)
Interest calculated 12 times/year. Standard for savings & CDs.
Annual (n=1)
Interest calculated once/year. Common for bonds.
More frequent compounding generally results in higher returns because interest is added to your principal more often.
- Enter Initial Deposit (P): Start with the amount you're investing.
- Choose Frequency (n): Select daily, monthly, quarterly, or annually.
- Set Interest Rate (r): Enter the annual rate (e.g., 5%).
- Specify Time (t): How long will your money grow?
- Add Contributions: Optional regular deposits.
Quick Example:
$10,000 at 5% annual interest, compounded monthly for 10 years, with $100 added at the end of each month = $31,998.32 total value ($22,000 deposited, $9,998.32 interest earned).
Results use the standard formula A = P(1 + r/n)^(nt) plus the future value of a series for regular contributions. Rates are nominal annual rates and regular contributions are added at the end of each period, unless you choose otherwise.
- $10,000 at 5%, compounded monthly for 10 years, $100 added each month: $31,998.32.
- $10,000 at 6%, compounded monthly for 10 years, $200 added each month: $50,969.84.
- $10,000 at 5%, compounded monthly for 10 years, no deposits: $16,470.09.
You can reproduce each of these with the inputs above. Last reviewed November 2026.
- $10,000 start, $500 added monthly, 7%, 30 years? About $691,150.47 (monthly compounding, deposits at month end).
- How much to invest monthly to reach $1,000,000 in 20 years at 7%? About $1,919.66 a month from zero; use the Goal-Based tab to solve it with your own starting balance.
- $500,000 and $3,000 withdrawn monthly at 6%, how long will it last? Just under 30 years on this site's assumptions; see the calculator with withdrawals.
- Daily vs monthly compounding on $10,000 at 5% for 10 years? Annual $16,288.95, monthly $16,470.09, daily $16,486.65.
- Can I add deposits and withdrawals? Deposits are in the main calculator; withdrawals have their own page because they change the answer from growth to depletion time.
Rates are nominal annual rates. Last reviewed November 2026.
A compound interest calculator is a financial tool that helps you calculate how your money grows over time when interest is added to your principal and then earns interest itself. Unlike simple interest calculators that only calculate interest on the principal, a compound interest calculator accounts for the exponential growth that occurs when interest compounds.
Our compound interest calculator supports multiple compounding frequencies:
- Daily compounding: Interest calculated 365 times per year
- Monthly compounding: Interest calculated 12 times per year
- Quarterly compounding: Interest calculated 4 times per year
- Semi-annual compounding: Interest calculated 2 times per year
- Annual compounding: Interest calculated once per year
This makes it ideal for calculating investment growth, savings account returns, loan interest, and retirement planning scenarios.
Yes! Our compound interest calculator is 100% free with no registration, sign-up, or hidden fees required. You can calculate unlimited scenarios for your investments, savings, loans, or retirement planning without any cost.
We believe financial planning tools should be accessible to everyone, whether you're learning about compound interest or planning your own savings.
What you get for free:
- Unlimited calculations with no restrictions
- Support for all compounding frequencies
- Regular contribution calculations
- Detailed breakdown of results
- No personal information required
The calculator applies the standard compound interest formula for the frequency you choose, including regular contributions. Real accounts can differ slightly: banks may round at each period, credit interest on different days, or change the rate over time. Use the results as a projection, not as a quote from your bank.
If you use an annual interest rate but select a monthly compounding frequency, the calculator will divide the annual rate by 12 to calculate the monthly rate. For example, an annual rate of 12% would be converted to a 1% monthly rate.
You can select the desired compounding frequency from the dropdown menu. The available frequencies are daily, monthly, quarterly, semiannually, and annually.